
Insurance Coverage for Bariatric Surgery: What Every Patient Needs to Know
Quick Answer
Watch Related Video
One belief keeps many patients from ever scheduling a consultation: the assumption that their insurance will not pay for weight loss surgery.
That hesitation is understandable. Few people know what their policy includes, which steps it demands, or who to call first, so the question never gets asked. Meanwhile, obesity remains a treatable disease, and the treatment may well be a covered benefit that the patient simply never confirmed.
The scenario I find most frustrating as a surgeon goes like this. A patient phones the insurer and a representative confirms that bariatric surgery is covered. Reassured, the patient spends months on supervised weight-loss visits, a psychological evaluation and nutrition counseling. When the surgical request is finally submitted, it is denied. The patient qualified medically and did every step correctly. The denial happened because that particular plan excludes weight loss surgery, even though the same insurer covers it under other plans.
This is the most common and most costly pitfall in bariatric insurance, and the rest of this article explains how to avoid it.
Why the "95% Coverage" Figure Is Misleading
Many websites, some bariatric practices among them, repeat the claim that "95% of insurance companies cover bariatric surgery." The figure originates from a survey of the 64 largest private insurers in the United States. Strictly speaking it is accurate: 95% of those companies maintain a written medical policy for bariatric surgery that spells out when they will and will not approve it.
A medical policy, however, does not guarantee that a given plan pays for the operation. Take Blue Cross Blue Shield as an example. Its bariatric policy states that the procedure is medically appropriate for patients who meet certain criteria. Your employer, though, picked one particular Blue Cross plan for its workforce, and that plan may carry a specific bariatric surgery exclusion. Such an exclusion takes priority over every medical criterion. A BMI of 45 combined with diabetes and sleep apnea makes no difference; an excluded benefit stays excluded.
Gaps like this help explain why roughly 1% of people who are eligible for bariatric surgery in the United States go on to have it. Studies also report that 22% of candidates who are medically appropriate are refused insurance reimbursement, and that their risk of death rises three-fold as a consequence. The stakes are far higher than a paperwork inconvenience.
The useful question, then, is not whether your insurer covers bariatric surgery. It is whether your own plan covers it and whether that plan contains an exclusion.
Two Questions to Ask Your Insurer
Every call to your insurance company should include two separate questions, asked in the order below.
First, ask whether your particular plan provides benefits for bariatric surgery or for metabolic and bariatric surgery procedures.
Pay close attention to the reply. Only an unambiguous yes counts. If the representative hedges or needs to look into it, stay on the line until you get a firm answer.
Second, ask the question most callers skip: whether your plan contains a specific exclusion for bariatric surgery, weight loss surgery or obesity surgery.
This second question can spare you months of effort. Representatives often open the insurer's general medical policy, see that bariatric surgery is covered, and answer yes. They may never check, or never mention, that your employer added a plan rider excluding bariatric procedures. In that case the insurer covers the surgery, but your plan does not.
Patients come to us with this story again and again. They devote three, six or even twelve months to supervised weight loss, a psychological evaluation, laboratory tests and clearances, only to receive a letter citing an "excluded benefit." That wording is different from "doesn't meet criteria." It means approval was never possible, regardless of how much work they put in.
For that reason, our practice completes a thorough insurance verification before any patient begins the preoperative steps. Rather than stopping at the insurer's policy, we obtain the actual plan documents, search them for exclusions and confirm the specific benefits. Our goal is to make sure no patient spends months on a process that could never end in approval.
If the program you are considering does not verify coverage this carefully, request that it does, or verify it on your own. Put both questions to your insurer, ask for the answers in writing, and request the exact section of your plan document that covers bariatric surgery. A verbal confirmation from a call-center representative is not enough to rely on.
Where Exclusions Come From and Who They Affect
Exclusions are a product of the way health insurance is structured in the United States.
Most people with private coverage receive it through work, and the employer decides which services the plan includes and which it leaves out. Employers with more than 500 employees frequently self-insure: they pay claims with their own funds and hire an insurance company only to administer the plan. Federal law, rather than state law, governs these self-insured plans. As a result, a state law requiring bariatric surgery coverage may not reach your plan at all if your employer self-insures.
State mandates are also uncommon. According to the latest available data, only about 5 states require state-regulated health plans to cover bariatric surgery. Under the Affordable Care Act, 23 states designated bariatric surgery an Essential Health Benefit; however, this rule applies only to individual and small-group plans bought on the marketplace or offered by small employers. Large employer plans, which cover most insured Americans, are not subject to it.
Put together, the insurer may maintain a bariatric policy and your state may or may not require coverage, but the decision that actually settles the matter is your employer's choice to include or exclude bariatric surgery in your plan.
Employees often believe that a workplace wellness program means weight-loss procedures will be reimbursed, yet coverage is frequently missing. In one study, most respondents said they had no health coverage for obesity treatment, even at employers whose wellness programs specifically focused on BMI. This gap in coverage is a real one.
BMI Requirements When Your Plan Includes Coverage
Suppose both answers came back favorable: your plan includes bariatric surgery and carries no exclusion. The next step is understanding the qualifying criteria.
Most insurers continue to rely on criteria drawn from the National Institutes of Health guidelines published in 1991. By that standard, a BMI of 40 or more (about 100 pounds above ideal body weight) can qualify a patient whether or not other medical problems are present. A BMI of 35 or more can qualify a patient who also has at least one obesity-related condition, such as type 2 diabetes, high blood pressure, sleep apnea, heart disease or severe joint disease, among others.
The guidelines changed substantially in 2022, when the American Society for Metabolic and Bariatric Surgery and the International Federation for the Surgery of Obesity issued updated recommendations. They now advise offering bariatric surgery to anyone with a BMI of 35 or higher, with or without other health conditions, and considering surgery for patients with a BMI from 30 to 35 who have metabolic disease such as diabetes.
This matters because roughly 92% of private insurers have not caught up and still apply the 1991 criteria, leaving a gap between current medical evidence and what insurers approve.
For patients of Asian descent, the updated guidelines advise considering surgery at a BMI of 27.5 or higher, since metabolic disease appears at lower BMIs in this population.
Requirements Beyond BMI
Qualifying by BMI is only the starting point. Most insurers add further conditions before they approve surgery. The most common are listed below.
1. A medically supervised weight-loss program. This is the most demanding requirement, and 87% of private insurance policies include it. It usually involves monthly physician visits, with your primary care doctor or a weight-management specialist, to record your weight, provide dietary counseling and track progress. Commercial plans require an average of about 3 to 4 months, Medicaid plans generally require more time (roughly 6 to 7 months on average), and some plans ask for 6 to 12 months.
In fairness to patients, I should point out that medical evidence does not strongly show that these required waiting periods improve surgical results. Several studies have found that insurer-mandated preoperative weight-loss programs are not linked to better outcomes one or two years after surgery. Research has also found that requiring 3 to 6 months of supervised weight management significantly lowered the odds that patients went on to have surgery, not because they were ineligible but because the hurdle discouraged them. Even so, when your plan requires the program, it must be completed, so begin it as soon as you can.
2. A psychological evaluation. Roughly 75% of insurance policies call for a mental health assessment before surgery. It is not an exam you pass or fail; it confirms that you understand the operation, hold realistic expectations and have support in place.
3. A nutritional evaluation. Most programs ask you to see a registered dietitian before surgery, and many patients find this one of the most helpful parts of preparation.
4. Medical clearance. Based on your health history, you may need clearance from a cardiologist, a sleep study, blood tests or other assessments.
5. A letter of medical necessity. The surgical practice sends your insurer documentation explaining why surgery is medically necessary in your case.
Medicaid deserves a specific note. Studies show Medicaid patients face the greatest number of preoperative requirements, about 4 on average, compared with about 2 to 3 for commercial plans, along with the longest supervised weight-loss periods. The result is a genuine inequity in access to care.
Medicare and Medicaid Coverage
Medicare beneficiaries are in a favorable position. A National Coverage Determination has provided Medicare coverage for bariatric surgery since 2006, including sleeve gastrectomy and gastric bypass performed at an accredited center. Patients qualify with a BMI of 35 or higher plus at least one obesity-related condition. The hospital must be enrolled in a nationally recognized accreditation program, and complication rates at accredited centers are significantly lower.
Medicaid coverage depends on the state. In 2017, 49 of the 50 state Medicaid programs reported covering bariatric surgery, compared with 45 states in 2009. Their requirements can be more extensive, as described above, so Medicaid patients should contact their plan directly and request its bariatric surgery criteria in writing.
If Your Request Is Denied
Denials come in two distinct forms, and the right response depends on which one you receive.
Criteria denial. Your plan includes bariatric surgery, but the insurer believes a requirement was not met. Perhaps a month of supervised weight loss is missing, a document was incomplete or a code was entered incorrectly. Denials of this kind can be appealed, and many are reversed.
Excluded-benefit denial. Your plan does not include bariatric surgery at all. Because this is a benefits decision made by your employer rather than a medical judgment, it cannot be appealed on medical grounds.
For a criteria denial, start by reading the letter closely, since it states the specific reason. Partner with your surgeon's office; an experienced bariatric program has staff who manage appeals routinely. Submit a formal appeal that includes your full weight history, every comorbidity with supporting lab work, records of all prior weight-loss attempts and letters from your physicians. If that appeal fails, pursue a second-level appeal, and you may also request that an independent outside reviewer examine the decision.
An excluded-benefit denial calls for a different approach. Ask your employer's human resources department whether bariatric coverage could be added when the plan renews. During open enrollment, see whether your employer offers another plan that includes it. Consider self-pay. And speak up, since employers become more likely to add coverage as more employees ask for it.
Paying for Surgery Yourself
When insurance is not an option, patients can choose to self-pay. Nationally, the median cost is about $10,900 for sleeve gastrectomy and about $13,600 for gastric bypass. Prices differ widely from one region and hospital to another, and financing is often available.
It also helps to weigh the long-term picture. Treating obesity and its complications over a lifetime, including diabetes and blood pressure medications, CPAP equipment, joint replacements and heart procedures, often costs far more than a single operation. Some patients recover the cost of surgery within a few years through medication savings alone.
Step-by-Step Action Plan
If you are considering bariatric surgery, these are the steps to take next.
Step 1: Contact your insurer now and ask both questions: whether your plan covers bariatric surgery, and whether it has a specific exclusion for bariatric, weight loss or obesity surgery. Request both answers in writing.
Step 2: If possible, obtain your plan's Summary of Benefits and Coverage. Go to the exclusions section and search for the terms "bariatric," "weight loss surgery" or "obesity surgery."
Step 3: Ask any bariatric program you contact whether it performs a complete insurance verification. A well-run program reviews your actual plan documents, looks for exclusions and confirms your benefits before you begin any requirements. Our practice does exactly this, and it is the most important safeguard against wasted months.
Step 4: If coverage is confirmed, book a visit with your primary care doctor right away. Explain that you are pursuing bariatric surgery and ask that your weight, BMI and obesity-related conditions be recorded at each appointment. When a supervised weight-loss program is required, that visit can serve as its first month.
Step 5: Avoid trying to lose weight on your own before the first consultation in order to get healthier beforehand. If your BMI falls below the qualifying threshold before approval, you may no longer be eligible. Enter the process at your current weight.
Step 6: Begin your evaluations promptly. Book the psychological evaluation, the nutrition consultation and any required medical clearances as early as you can; they can frequently run alongside the supervised weight-loss program.
Common Questions About Coverage
How long does insurance approval take?
The timeline follows your plan's requirements. With a required 3-month supervised program, plan on about 4 to 6 months from the first appointment to surgery; with a 6-month requirement, about 7 to 9 months. Completing evaluations at the same time as the supervised program can shorten the wait.
What if my BMI is slightly below 35?
BMI can vary over time, and your surgeon's office will record your highest documented BMI. The 2022 ASMBS/IFSO guidelines support surgery at a BMI of 30 to 34.9 when metabolic disease is present, although most insurers have not adopted that threshold yet. Review your circumstances with a bariatric program.
Is revisional bariatric surgery covered?
Many plans cover it, often with stricter criteria. Expect to need records of the original operation, evidence of weight regain or insufficient weight loss, and a new letter of medical necessity.
Are post-surgery vitamins and supplements covered?
Over-the-counter vitamins and supplements are usually not covered, although some plans pay for prescription-strength vitamin D or iron when medically necessary. Plan on spending about $30 to $50 a month on bariatric-specific vitamins.
Is plastic surgery for loose skin covered?
Some plans cover a panniculectomy, which removes the apron of abdominal skin, when it causes documented medical problems such as rashes, infections or limits on function. Cosmetic contouring procedures, including tummy tucks, arm lifts and thigh lifts, are generally not covered.
Key Points to Remember
Obtaining insurance approval for bariatric surgery is more involved than many websites suggest. The often-quoted "95% of insurers cover it" refers to insurance companies, not to the plan you are actually enrolled in, and many plans contain exclusions that guarantee a denial no matter what steps you complete.
The encouraging news is that once coverage is confirmed, the path to approval is clear and manageable, and you do not have to navigate it by yourself. An experienced bariatric program will verify your benefits before you spend a single month on requirements.
What most often stands between patients and this operation is not insurance itself but uncertainty about how insurance works. With these steps, you can get clear answers early and avoid a preventable setback on the way to a treatment that can improve both the length and the quality of your life.
Further Information
For additional context and a deeper professional perspective, you can read the companion LinkedIn article linked below.
Insurance coverage reflects recognition of obesity as a chronic disease requiring medical and surgical treatment. Coverage criteria are intended to support safety, readiness, and long‑term support.
Medical Topics Covered
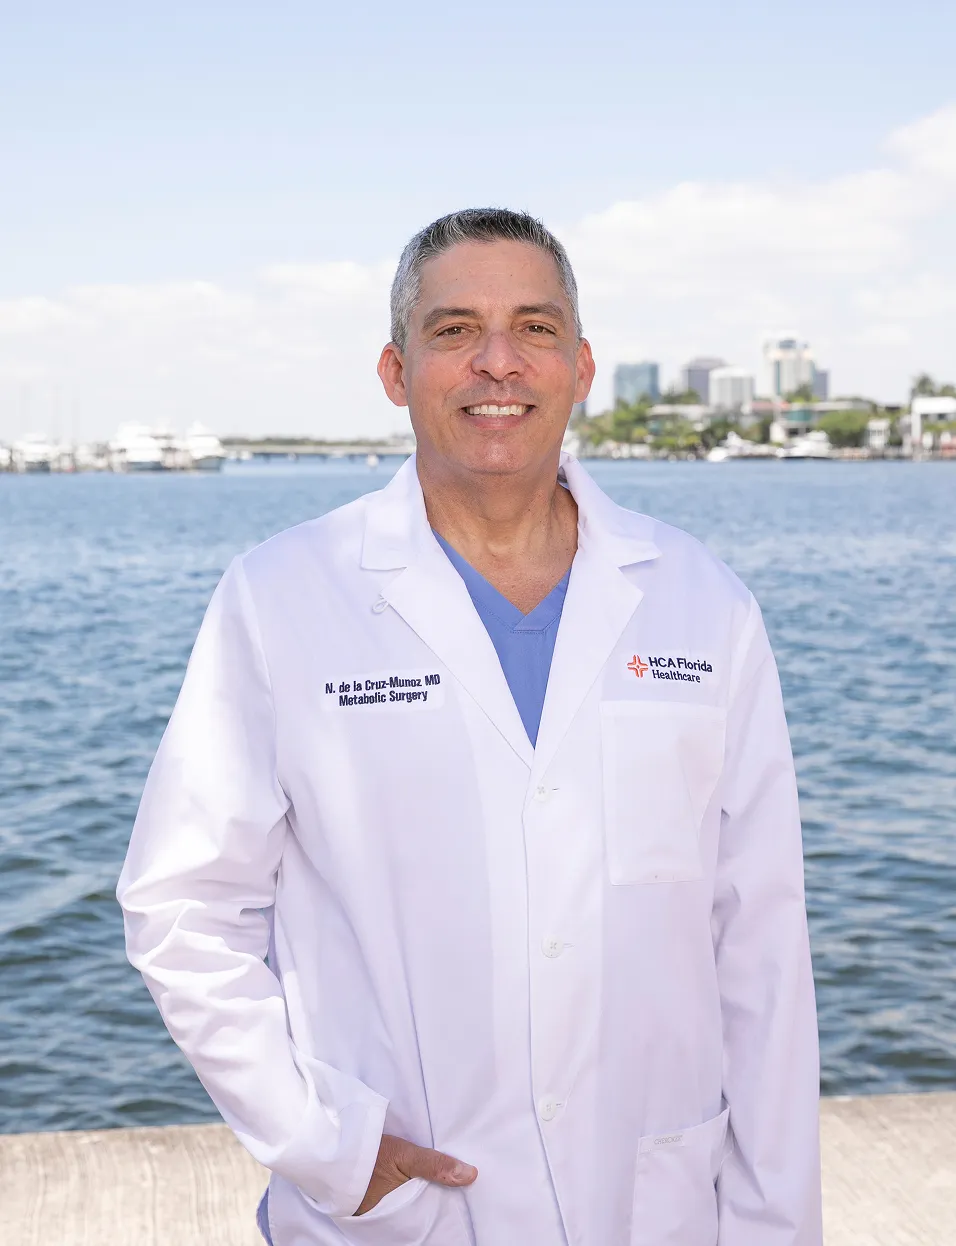
Dr. de la Cruz‑Muñoz specializes in advanced minimally invasive and robotic surgery, metabolic disease management, and comprehensive long‑term patient care. His work integrates clinical expertise, academic leadership, and a commitment to evidence‑based medicine. He has trained surgeons across the country, contributed to national guidelines, and is widely regarded for his outcomes, innovation, and patient‑centered approach.
Patients choose Dr. de la Cruz‑Muñoz for his combination of surgical excellence, metabolic expertise, and lifelong dedication to improving patient health through compassionate, high‑quality care.
Procedures We Offer
Conditions

FAQ
Insurance plans set their own coverage policies, which may rely on older criteria or add plan-specific requirements. These can include documentation of supervised weight-management programs or other conditions. Coverage varies by policy, so check your plan’s current requirements and ask your bariatric team about documentation and appeal options.
Many Florida insurance plans cover revisional surgery when it is medically necessary — for example, to treat complications, severe reflux, ulcers or strictures — and some cover revision for weight regain when criteria are met. Policies vary, and some limit coverage to one bariatric operation per lifetime. Our office reviews your plan, gathers documentation and handles prior authorization.
Coverage depends on your plan and the procedure. Medically necessary operations — such as hernia repair, gallbladder removal, anti-reflux surgery, myotomy for achalasia and cancer surgery — are generally covered, subject to your deductible and coinsurance. Bariatric surgery is covered by many plans when you meet their criteria, though some employers exclude it, and newer procedures such as SADI-S may require additional review. Endoscopic weight-loss procedures are often self-pay. Our office verifies your benefits and handles prior authorization before surgery.
In most cases, yes. Repair of a ventral, incisional or recurrent hernia is considered medically necessary when the hernia causes pain, limits activity, or risks incarceration, and most plans cover it subject to your deductible and coinsurance. Many insurers require prior authorization, and some components — such as removing excess skin at the same time — may be considered cosmetic and covered differently. Our office verifies your benefits and obtains any needed authorization before surgery.
Coverage depends on the treatment and your plan. Many Florida plans cover bariatric surgery when criteria are met. Coverage for weight-loss medications varies widely — some plans cover them with prior authorization, while others exclude them. Endoscopic procedures such as gastric balloons and endoscopic sleeve gastroplasty are usually self-pay. Our office reviews your benefits and explains costs before you start.
Yes. Many Florida insurance plans cover metabolic and bariatric surgery when criteria are met, especially for patients with obesity and related conditions such as type 2 diabetes, sleep apnea or hypertension. Some plans still use older BMI criteria that differ from current medical guidelines. Our office verifies your benefits and explains any requirements, such as nutrition visits or medical clearance.
Yes. Many insurance plans in Florida cover bariatric surgery when you meet their criteria, including Medicare and many commercial and employer-sponsored plans. Coverage depends on your specific policy — some employers exclude weight-loss surgery — and most plans require documentation such as BMI history, related health conditions, nutrition visits and medical clearance. Our office verifies your benefits and helps you complete the requirements for approval.
Most patients return to normal daily activities within one to two weeks after gastric bypass or sleeve gastrectomy and within two to three weeks after SADI-S or duodenal switch. Hospital stays are usually one to two nights. Because blood sugar and blood pressure can fall quickly, diabetes and blood pressure medications are adjusted closely in the first weeks.
Most patients return to normal activities within one to two weeks after sleeve gastrectomy or gastric bypass, and within two to three weeks after SADI-S or duodenal switch. Hospital stays are typically one night. Full exercise usually resumes at four to six weeks, and regular foods at about six to eight weeks.
Most patients go home after one night and return to normal daily activities within one to two weeks. Desk work usually resumes in one to two weeks and physical work in four to six weeks. Expect fatigue early on as your body adjusts to fewer calories; meeting your protein and fluid goals helps. Structured exercise usually begins at four to six weeks.
The program accepts major insurers and works directly with your plan to determine coverage and obtain authorization. Coverage depends on your specific policy and whether bariatric surgery is included, and out-of-network rules may apply when you travel. The office verifies your benefits before you commit to travel and explains any out-of-pocket costs or self-pay options.
People Also Ask
Obesity is recognized as a chronic disease by major medical organizations, including the American Medical Association. It is influenced by genetics, hormones, brain signaling, environment, sleep, stress and medications — not simply willpower. Like other chronic diseases, it often requires long-term treatment, which may include nutrition, activity, behavioral support, medications and surgery. Lifestyle matters, but biology largely determines how the body responds.
The body has powerful systems that defend its weight. When you lose weight, hunger hormones rise, fullness hormones drop, the brain becomes more focused on food and metabolism slows — a process called metabolic adaptation. Genetics, sleep, stress, medications and the modern food environment add to the challenge. These are biological forces, not character flaws, which is why medical treatment is often needed.
Genetics play a major role. Studies of twins and adopted children suggest that roughly 40–70% of the variation in body weight is inherited, influencing appetite, fullness, metabolism and where fat is stored. Many genes each contribute a small effect, and a few rare single-gene forms cause severe early obesity. Genes interact with environment, sleep, stress and medications, so a family history raises risk but does not determine destiny.
GLP-1 medications mimic a natural gut hormone released after eating. They act on the brain to reduce hunger and increase fullness, slow stomach emptying so meals last longer, quiet "food noise," and improve insulin release and blood sugar. Tirzepatide also acts on a second hormone, GIP. In clinical trials, these medications produced average weight loss of about 15–20% (Wilding et al., New England Journal of Medicine, 2021; Jastreboff et al., New England Journal of Medicine, 2022).
Yes. Obesity is associated with more than 200 health conditions, including type 2 diabetes, high blood pressure, high cholesterol, heart disease, stroke, sleep apnea, fatty liver disease, reflux, osteoarthritis, infertility and PCOS, depression and at least 13 types of cancer. Losing weight — through medical treatment or bariatric surgery — improves or resolves many of these conditions.
Dieting alone usually cannot overcome the body's biological defenses against weight loss. As weight falls, hunger hormones rise, fullness hormones fall and metabolism slows — changes that can last for years. Most people regain the majority of diet-related weight loss within several years. That is not a failure of willpower, and it is why treatments that address appetite biology, such as GLP-1 medications and bariatric surgery, are more effective for many people with obesity.
Consider medical evaluation when excess weight affects your health, mobility or quality of life, or when you have related conditions such as prediabetes, diabetes, high blood pressure, sleep apnea, fatty liver or joint pain. Guidelines support medications for adults with a BMI of 30 or higher, or 27 or higher with a weight-related condition, and surgery for a BMI of 35 or higher, or 30 or higher with metabolic disease. Early treatment can help prevent complications.
Yes. Bariatric surgery treats the biological drivers of obesity, changing hunger and fullness hormones, insulin sensitivity and the weight the body defends. It is the most effective and durable treatment for severe obesity, producing large, sustained weight loss and improving or resolving diabetes, high blood pressure, sleep apnea and fatty liver. Long-term studies show it also reduces the risk of heart disease, cancer and early death.